The next phase of packaging growth will not be driven by one material replacing another, but by putting each material in the right application and continuing to increase customer value.
BIOTEN Packaging Industry Insights / PAPER PACKAGING STUDY
Once materials are used where they fit best, growth must ultimately be validated by profit, cash flow and repeat orders.
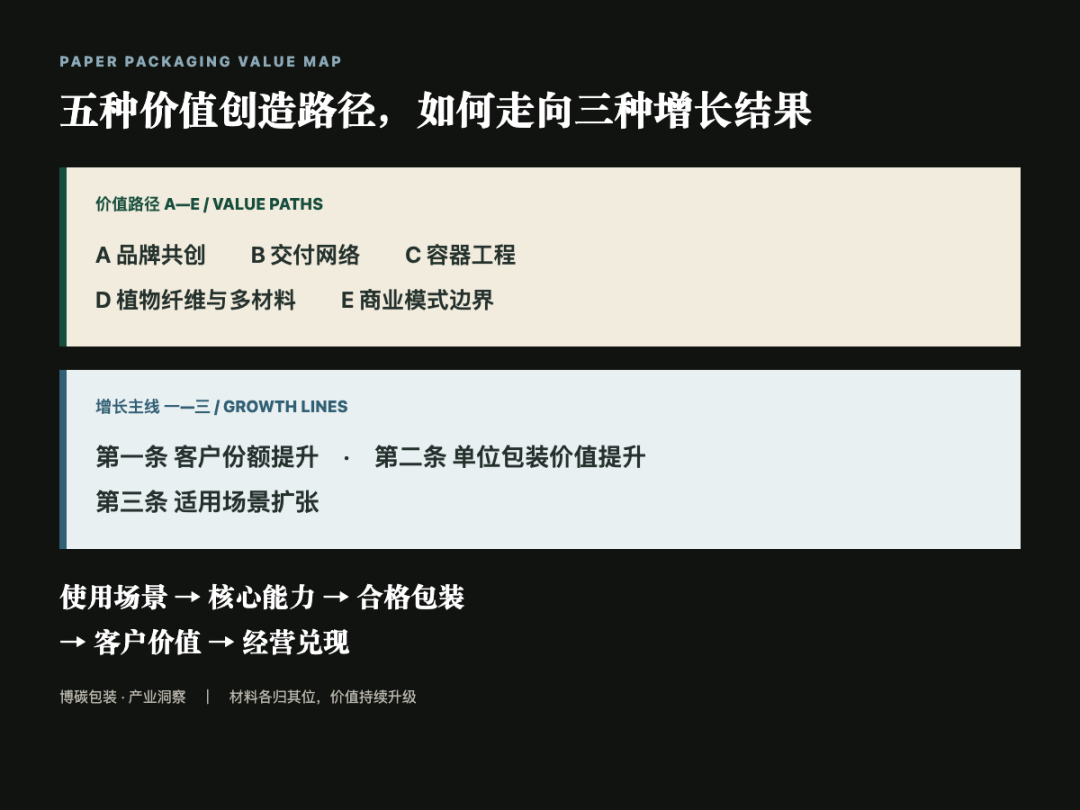
Manufacturing capability → Qualified packaging → Customer value → Business results
EDITORIAL QUESTION
Research question | This is not a question of material substitution, but of value realization.
Discussions of growth in the packaging industry are easily reduced to a single question: “How much plastic can paper replace?” Yet customers do not actually buy a position on materials. They buy packaging that protects its contents in real-world applications, runs reliably in production, is delivered on time, meets compliance requirements and controls total cost.
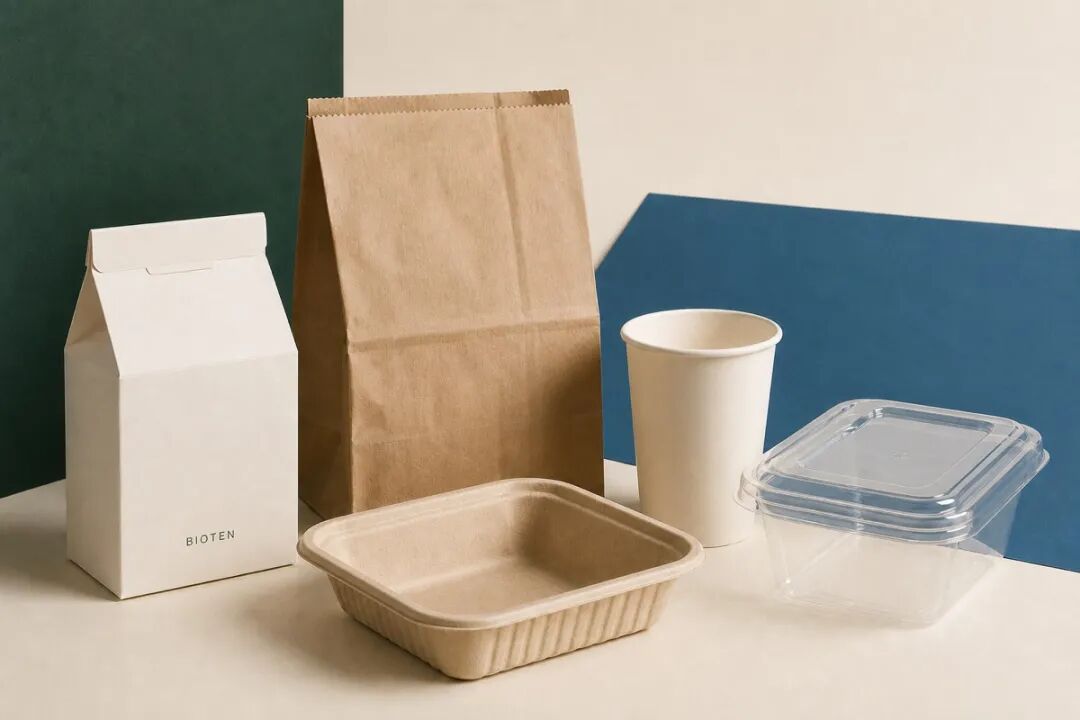
Plastics remain clearly suited to applications requiring high barrier performance, toughness, low weight, transparent presentation or complex sealing. Fiber-based packaging can assume more functions in suitable applications through fiber structures, functional layers, structural design and forming processes. The next opportunity is not to make one material occupy every position, but to put each material where it performs best so that every function creates clearer customer value.
The more useful question is this: how can companies turn their existing manufacturing capabilities into outcomes that customers are willing to purchase repeatedly? This article examines 10 purposively selected companies through one analytical sequence:
Use scenario → Core capability → Qualified packaging → Customer value → Business results
The five value-creation pathways are neither a ranking nor five mutually exclusive boxes. They address the same question: through which primary interface does a company’s most distinctive capability enter the customer’s operation, and which business outcomes ultimately validate it?
CORE JUDGEMENT
Core judgement
The next phase of growth in fiber-based packaging does not depend on one material occupying every position. It depends on whether a company can organize design, materials, manufacturing, delivery and compliance into outcomes that customers are willing to purchase repeatedly. The pathways may differ, but the criteria remain the same: deeper customer relationships, higher value per unit, broader application scope, and ultimately profit, operating cash flow and repeat orders.
Once materials are put in their proper place, the real differentiator is a company’s ability to keep turning qualified packaging into customer value.
SCOPE & METHOD
Scope of the study
These 10 companies are core observation samples selected for a specific purpose. They are not a ranking, not a “top 10” and not a complete representation of the industry. Six additional companies are used as peer evidence under three growth themes. They are not renumbered and do not form a second list; they merely show that similar customer-value mechanisms also occur at other points in the industry. Companies with different scales, product portfolios and market definitions are not compared mechanically. This article focuses on packaging converting, food packaging and consumer packaging companies; it does not compare upstream papermakers and packaging manufacturers at the same analytical level.
Project plans, exhibition displays, participation in standards, production licences and certification records prove only the stated stage and scope. They do not automatically demonstrate volume orders, market position or sustained profitability. “Growth” must ultimately be tested through the depth of customer relationships, value per unit, application scope, gross profit, profit, operating cash flow and repeat orders.
FIVE VALUE PATHS
Five value-creation pathways | First, examine how capabilities enter the customer’s operation.
Value path / CAPABILITY PATH
A
BRAND CO-CREATION
High-value brand packaging and customer co-creation
The value of brand packaging lies not only in printing and appearance, but also in whether a supplier can participate in the new-product process, reproduce creative, structural, color and process requirements reliably at scale, and turn a single order into a long-term supply relationship. The transferable lesson is that design becomes customer value only when a manufacturing system can reproduce it consistently.
Company case / CASE 01
GLOBAL BRAND DELIVERY
YUTO TECH.: Replicating brand solutions in global mass production
Brand co-creation | Engineering conversion | Cross-regional replication
Core capability | YUTO organizes creative design, structural engineering, R&D sampling, color management, lean manufacturing, procurement, warehousing and logistics into an integrated mass-production chain, enabling different capabilities to work together toward the same customer outcome.
Customer value | A new brand product must not only be designed; it must also reach different markets with consistent quality, timing and delivery standards. YUTO’s cross-regional network provides the organizational foundation for this replication and reduces the coordination cost of converting a concept into mass production.
Business results | In 2025, the company recorded revenue of RMB 17.238 billion, up 0.47% year on year; net profit attributable to shareholders of RMB 1.592 billion, up 13.05%; and net cash generated from operating activities of RMB 2.737 billion, up 38.23%. Overseas revenue reached RMB 6.131 billion, accounting for 35.57% of total revenue and increasing 20.27% year on year. R&D investment was RMB 737 million, or 4.28% of revenue, down slightly by 0.91% year on year. Taken together, these figures show broadly stable revenue, improved profitability and cash returns, and continued overseas expansion.
BIOTEN observation | At interpack 2026, the company presented FluoZero® grease-resistant technology and Ecocoon™ dry-formed plant-fiber cushioning material. At this stage, they are best understood as application reserves. Commercial realization should next be assessed through mass-production adoption, additional product categories from existing customers, gross margin and repeat orders.
Sources: YUTO TECH. 2025 Annual Report; YUTO TECH. interpack 2026 presentation materials
Company case / CASE 02
FLEXIBLE MANUFACTURING
ZRP: Turning brand iteration into a flexible manufacturing response
Structural R&D | Color management | Flexible response
Core capability | ZRP’s most distinctive capability is flexibility: structural R&D, color management, process development, digital-printing interfaces and cross-site manufacturing all support the frequent iteration required by brand customers.
Customer value | When multiple batches, short runs, personalization and rapid replenishment become routine, customers need more than speed. They also need color consistency, structural reliability and stable mass production. ZRP translates brand changes into an orderly manufacturing response, providing a more flexible route for new-product iteration.
Business results | In 2025, the company recorded revenue of RMB 3.167 billion, up 13.85% year on year; net profit attributable to shareholders of RMB 153 million, up 6.82%; net cash generated from operating activities of RMB 339 million, up 27.18%; and R&D investment of RMB 128 million, up 18.21%. Growth in scale, profitability, cash flow and R&D investment provides a positive foundation for further development of flexible manufacturing.
BIOTEN observation | The digital-printing partnership disclosed by the company adds capabilities such as single-sheet minimum runs, personalization and rapid replenishment, but the partnership itself does not prove incremental orders. The more meaningful indicators are sample lead time, first-pass color consistency across sites, additional SKUs from the same customer, and the gross margin and repeat orders achieved after R&D outcomes enter stable mass production.
Sources: ZRP 2025 Annual Report; ZRP digital-printing partnership materials
Value path / CAPABILITY PATH
B
DELIVERY NETWORK
Scaled manufacturing networks and supply-chain delivery
Corrugated boxes, paper bags and packaging for chain stores share one feature: customers buy certainty as well as products. The value of a network does not lie in the number of factories alone, but in whether orders can be scheduled, delivered reliably and fulfilled at a reasonable total cost. The transferable lesson is that distributed capacity creates delivery value only when it is organized as a coordinated network.
Company case / CASE 03
DELIVERY NETWORK
Hexing Packaging: Delivering certainty through a short-radius network
Multiple sites | Short radius | Order scheduling
Core capability | Hexing connects a multi-site network located close to customers with paper procurement, order scheduling, VMI, CPS and packaging logistics services, enabling short-radius, time-sensitive delivery of corrugated packaging.
Customer value | This network can reduce uncertainty during peak seasons, promotions, multi-plant supply arrangements and temporary order transfers. Hexing’s advantage is not simply that it has capacity, but that it organizes distributed nodes into a coordinated and responsive delivery system.
Business results | In 2025, the company recorded revenue of RMB 10.194 billion, down 11.13% year on year; net profit attributable to shareholders of RMB 103 million, up 10.61%; a consolidated gross margin of 13.02%, up 1.00 percentage point; and net cash generated from operating activities of RMB 258 million, down 53.07%. Improved profitability despite lower revenue demonstrates operating resilience, while the change in cash flow shows that network efficiency must still be converted into higher-quality collections.
BIOTEN observation | The annual report includes the company’s Thailand, Vietnam and Indonesia sites in its 2026 plan to accelerate capacity ramp-up and efficiency improvement. A plan is not a realized contribution. Its value must be demonstrated jointly by capacity utilization, order sources, on-time delivery, the profitability of overseas subsidiaries and operating cash flow.
Sources: Hexing Packaging 2025 Annual Report
Company case / CASE 04
MULTI-SKU DELIVERY
Nanwang: Keeping multi-SKU manufacturing aligned with store rhythms
Multiple categories | Store rhythm | Regional response
Core capability | Nanwang organizes multi-SKU manufacturing and regional delivery around paper bags, food packaging, nonwoven bags, labels and receipts. It addresses the “many, fast and changing” rhythm of chain stores, where product launches, promotions and replenishment all require a synchronized manufacturing response.
Customer value | A multi-material, multi-node footprint gives customers more choice in their store-packaging mix. Evaluation must nevertheless distinguish between material categories rather than using growth in one category as a proxy for another category’s performance.
Business results | In 2025, food-packaging revenue was RMB 604 million, up 13.01% year on year, with a gross margin of 14.94%, up 1.36 percentage points. Paper-bag revenue was RMB 576 million, down 11.91%, with gross margin down 8.33 percentage points. Nonwoven-bag revenue reached RMB 479 million, up 185.59%, making it the group’s main source of incremental revenue. Group revenue was RMB 1.759 billion, up 25.60%, while the net loss attributable to shareholders was RMB 26.4315 million. Net cash generated from operating activities was RMB 157 million, up 257.36%; the company stated that the increase was influenced by both sales collections and government grants.
BIOTEN observation | A more complete view of the operating quality of Nanwang’s multi-category network will come from the recovery of paper-bag revenue and gross margin, continued profitability in food packaging, capacity utilization at its paper-products projects and nonwoven nodes, regional order density, and progress toward sustained profitability.
Sources: Nanwang 2025 Annual Report
Value path / CAPABILITY PATH
C
CONTAINER ENGINEERING
Food-service applications and container engineering
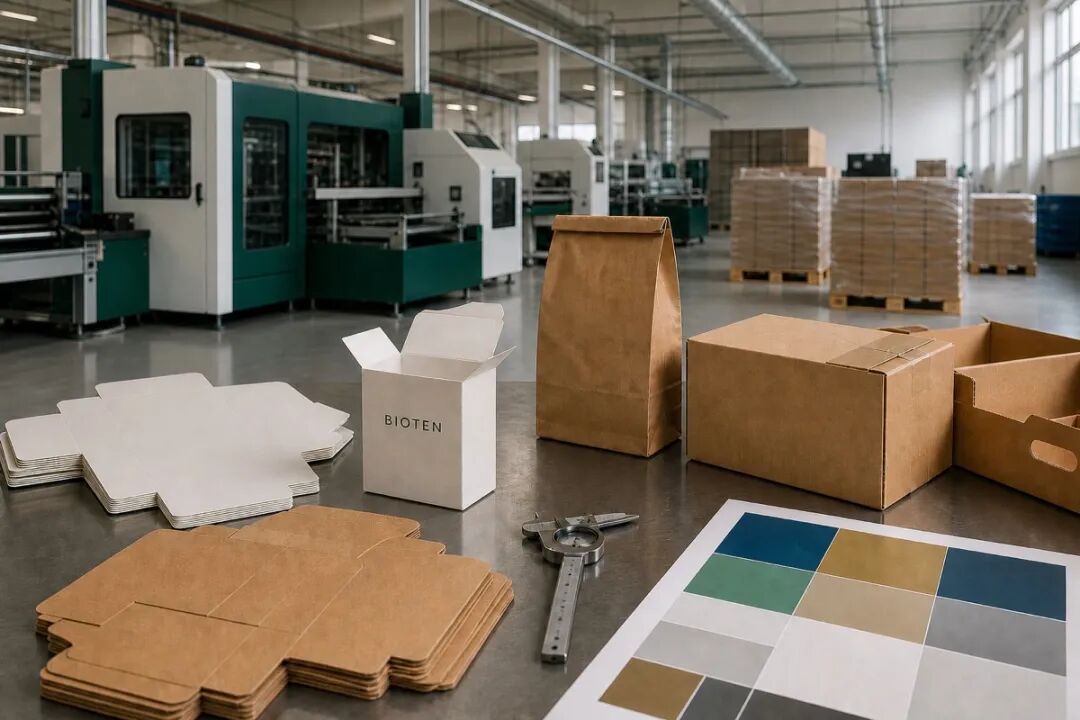
A food container is not simply a formed material. Sealing, leak resistance, barrier performance, freshness preservation, printing, heat sealing, stacking and line speed must all work together in one product. Food-contact and end-of-life claims must also correspond to the specific structure and target market. The transferable lesson is that material innovation becomes a dependable solution only after it has passed through the finished product and the commercial production line.
Company case / CASE 05
VERTICAL MANUFACTURING
Hengxin Life: Connecting material expertise with finished-product forming
Material modification | Coating and sheet extrusion | Finished-product forming
Core capability | Hengxin deserves recognition not for a single “PLA biodegradable” label, but for integrating resin modification, coating, sheet extrusion, printing, forming and logistics management into one manufacturing system. It translates the order language of food-service ware into quantifiable production at scale, allowing service, channel, platform and user-experience requirements to be calibrated repeatedly in the finished product.
Customer value | For food-service ware customers, vertical coordination can shorten repeated adjustment between materials and processes and support a more stable supply of products such as paper cups and bowls. The real value lies not in the material name itself, but in yield, performance in use and reliable volume delivery.
Business results | In 2025, the company recorded revenue of RMB 1.845 billion, up 15.73% year on year; net profit attributable to shareholders of RMB 224 million, up 1.80%; net profit attributable to shareholders excluding non-recurring items of RMB 181 million, down 15.44%; and net cash generated from operating activities of RMB 340 million, down 9.17%. Revenue from biodegradable products was RMB 915 million, accounting for 49.62% of total revenue and increasing 4.95% year on year. The category’s gross margin was 26.25%, down 4.81 percentage points. Growth in scale is already visible; the next priority is to convert category expansion more fully into recurring profit and higher value per unit.
BIOTEN observation | The annual report states that Hengxin has ranked among the top 10 companies in the “biodegradable plastics” category of China’s light-industry plastics sector for six consecutive years. It also states that a specified PHA-coated paper product obtained BPI home-compostability certification in January 2026. The former applies only to the stated specialist category; the material identity and date of the latter come from the company’s disclosure, while the exact SKU and Home Certified status must be verified in the BPI database. Awards and certifications are not evidence of orders. Stable orders, unit cost, yield and repeat purchases provide the evidence of commercial depth.
Sources: Hengxin Life 2025 Annual Report; BPI database entry for Hengxin products
Company case / CASE 06
FOOD CONTAINER ENGINEERING
Otor Technology: Making material selection serve the food application
Leakproof sealing | Barrier and freshness preservation | Multi-material choice
Core capability | Otor Technology uses thermoformed food containers as its platform and organizes solutions around sealing, leak resistance, barrier performance, freshness preservation, appearance and delivery close to customers, while retaining a paper-container interface. Its expertise lies not in betting on one material, but in selecting materials according to the contents, production method and required use outcome.
Customer value | Food manufacturing, prepared meals and on-the-go beverages require different container solutions. Otor Technology makes the material serve the application, enabling customers to choose the most appropriate structure for current performance, cost and manufacturing conditions. Such a candid and clearly defined capability boundary has more lasting value than a material label.
Business results | In 2025, the company recorded revenue of RMB 1.057 billion, down 3.95% year on year; net profit attributable to shareholders of RMB 76.16 million, up 11.35%; a consolidated gross margin of 19.45%, up 1.15 percentage points; and net cash generated from operating activities of RMB 140 million, down 39.48%. Plastic food containers accounted for 96.24% of revenue from principal operations and paper food containers for 2.63%. Capacity utilization for the two categories was 79.77% and 13.66%, respectively. Paper food containers had a gross margin of 17.57%, down 4.81 percentage points. Improved profitability despite lower revenue demonstrates resilience in container engineering; paper containers remain at the capability-utilization and commercial-validation stage.
BIOTEN observation | Plastic remains the company’s clear core business, while paper containers provide an interface for specific applications; this is not a “complete transition to paper.” The depth of its multi-material capability will be determined by improvements in sealing and leak resistance, customer adoption of different material solutions, capacity utilization and gross margin for paper containers, and the conversion of profit into cash.
Sources: Otor Technology prospectus, signed 19 May 2026
Company case / CASE 07
CUP CONVERSION
Lido: Bringing water-based coatings into real cup-converting processes
Functional layer | Complete cup format | Real production process
Core capability | Lido’s most distinctive capability is its cup-converting interface. It brings disposable paper cups and water-based barrier coatings into the full production process, including die-cutting, side sealing, bottom sealing, rim rolling, stacking and cup separation. For many years, it has worked with BASF, APP Sinar Mas and DBC to promote environmentally preferable water-based acrylic barrier coatings, earning the trust of premium markets in Europe, Australia and New Zealand. Lido has long focused on easy-to-recycle systems for water-based coated disposable paper cups and has also won long-term orders from coffee chains and well-known retailers in China.
Customer value | Lido advances the discussion from “Can the material sample work?” to “Can the complete cup be manufactured reliably?” For material suppliers and brands, this interface exposes issues involving cup-line speed, heat sealing, bottom sealing, nesting and cup separation earlier, bringing water-based coated-paper structures closer to real commercial lines.
Business results | Lido does not publish audited operating data on a consistent basis, so this article makes no judgement on its revenue scale, market ranking or customer share. Public evidence shows that the national standards platform lists it as a drafting organization for GB/T 44834—2024 and GB/T 27591—2025; Hunan’s licensing register lists a production licence for food-contact paper packaging, containers and related products; and the flustix database entry PF3R0016 covers paper cups, lids, bowls and plates and reports a recyclability assessment of 98%.
BIOTEN observation | Lido keeps the food-contact documentation chain for its paper cups visible to customers, an important safety baseline for premium and brand customers. Customer repeat orders and actual production and sales volumes continue to grow. Public activities demonstrate the practical value of moving material solutions into complete products. Because Lido is not listed, no public revenue figures were found. This study makes no claim about its industry ranking.
Sources: Lido website; GB/T 44834—2024; GB/T 27591—2025; Hunan production-licence materials; flustix certification database; and market and value-chain feedback
Value path / CAPABILITY PATH
D
FIBER + MULTI-MATERIAL
Plant fiber and multi-material platforms
Extending plant fiber into more applications requires pulp formulation, tooling, structural design, surface functionality, automation, yield and unit cost to work together. A multi-material platform must help customers make better choices among performance, regulation, cost and market demand. The transferable lesson is that a broader product line does not automatically create more value; it must be demonstrated by category-level profitability, utilization and repeat orders.
Company case / CASE 08
MOLDED FIBER SCALE
ZX Packing Group: Scaling plant-fiber manufacturing through a specialized system
Specialist focus | Scaled manufacturing | Cross-market replication
Core capability | ZX Packing Group has long focused on molded plant-fiber food-service ware, consolidating R&D, equipment, certification, manufacturing and customer service in one specialized system. Sustained focus allows similar orders to build cumulative experience in yield, efficiency and replication across markets.
Customer value | For customers, specialization means more than a concentrated product portfolio. It also means that equipment, tooling, materials and quality control are continually optimized around the same application family. ZX Packing Group has advanced plant fiber from a material direction to an observable scaled-manufacturing system; this industrial platform is its most valuable strength.
Business results | In 2025, the company recorded revenue of RMB 1.506 billion, down 2.62% year on year; food-service ware revenue of RMB 1.442 billion, down 4.97%; net profit attributable to shareholders of RMB 266 million, down 17.79%; and net cash generated from operating activities of RMB 417 million, up 30.36%. Its Thailand operation generated revenue of RMB 432 million and net profit of RMB 163 million, demonstrating an actual operating contribution from overseas manufacturing. The decline in revenue and profit must also be acknowledged: recovery in growth cannot be assessed from capacity expansion alone.
BIOTEN observation | The company’s 2026 interim earnings forecast estimates net profit attributable to shareholders of RMB 175 million to RMB 220 million, an increase of 50.22% to 88.85% year on year, and identifies the Thailand capacity footprint as an important factor supporting resumed supply to the US market. The forecast is unaudited and remains subject to the formal report. Key indicators for cross-market replication include sales volume and profit per tonne for food-service ware, utilization and cash contribution at the Thailand site, continuity of customer relationships, and the actual commissioning milestones of US projects.
Sources: ZX Packing Group 2025 Annual Report; ZX Packing Group 2026 interim earnings forecast
Company case / CASE 09
MULTI-MATERIAL PLATFORM
Homelink: Broadening customer choice through a multi-material platform
Material portfolio | Application selection | Category coordination
Core capability | Homelink brings conventional plastics, fully biodegradable materials, plant fiber and paper products together on one product platform, enabling customers to compare performance, regulation, cost and market demand. It turns material selection from a single-choice question into a portfolio decision.
Customer value | Different countries, channels and contents do not require the same solution. A multi-material platform lets customers configure product structures by application without committing to a predetermined route. Its real value is to shorten the selection and trial-and-error process while providing a one-stop, cross-category supply interface.
Business results | In 2025, the company recorded revenue of RMB 2.687 billion, up 15.53% year on year. Revenue from plant-fiber products was RMB 195 million, up 53.90% and accounting for 7.26% of group revenue. The group reported a net loss attributable to shareholders of RMB 75.71 million and a net loss attributable to shareholders excluding non-recurring items of RMB 192 million. Net cash generated from operating activities was RMB 113 million, down 66.53%; the company attributed the change mainly to increased working-capital requirements following the start-up of its Thailand factory. Observable demand for the new route is emerging, but the breadth of the platform must still be converted into category-level profitability and cash quality.
BIOTEN observation | Profit from the plant-fiber category is not disclosed separately, so profitability cannot be inferred directly from revenue growth. Plant-fiber capacity loading, unit cost at overseas sites, customer repeat orders, category-level gross margin, profit excluding non-recurring items and improvement in operating cash flow will determine whether the multi-material platform moves from “a broader product range” to “deeper solutions.”
Sources: Homelink 2025 Annual Report
Value path / CAPABILITY PATH
E
BUSINESS MODEL BOUNDARY
Extending the boundary between a manufacturing platform and digital commerce
The first four pathways primarily explain how packaging capabilities enter the customer’s operation. JIHONG CO provides a boundary case in business models: when packaging manufacturing and digital commerce operate in parallel, can each business first create value independently and then demonstrate synergy through measurable connections? The transferable lesson is that the value of diversified businesses is not created by stitching together a narrative, but by validating segment performance and genuine synergy separately.
Company case / CASE 10
MANUFACTURING + DIGITAL
JIHONG CO: Enabling two businesses to create value in their own right
FMCG packaging | Digital commerce | Parallel validation
Core capability | JIHONG CO operates both FMCG paper packaging and cross-border social e-commerce. Its packaging segment serves FMCG customers through design, cartons, paper bags, food packaging and multi-site manufacturing, while its digital business has built an independent cross-market operating capability. The parallel operation of these two businesses distinguishes it structurally from most packaging companies.
Customer value | Packaging customers receive stable manufacturing and category expansion, while the digital business brings the group closer to consumer and operating rhythms in different markets. A more professional and constructive interpretation of this model is to avoid assuming “natural synergy,” evaluate the two businesses separately and wait for measurable connections to emerge.
Business results | In 2025, the packaging business recorded revenue of RMB 2.345 billion, up 11.71% year on year, with a gross margin of 20.69%, up 2.84 percentage points. Paper-bag revenue increased 21.15% and food-packaging revenue increased 23.17%. Group revenue was RMB 6.722 billion, up 21.56%, and net profit attributable to shareholders was RMB 277 million, up 52.16%; however, net cash generated from operating activities was RMB 261 million, down 32.45%. Improvements in the packaging segment’s product mix and profitability are clear, while the group still needs to convert profit growth more fully into cash returns.
BIOTEN observation | Key indicators for judging whether “parallel” operations develop into “synergy” include new customers and repeat orders in food packaging and paper bags, cash contribution from the packaging segment, and whether the digital business produces verifiable customer referrals, demand insights or improvements in delivery efficiency.
Sources: JIHONG CO 2025 Annual Report
THREE GROWTH LINES
Three growth lines | Bringing different pathways back to the same set of business outcomes
The 10 core samples provide the analytical framework. Six peer companies are placed directly under the growth line that best explains their value, without creating another list or renumbering them. The point is not to ask “Which other companies are included?” but to observe how the same growth mechanism recurs at different positions in the industry.
Growth line / GROWTH LINE 01
Increasing share of customer spend: From supplying one product to providing deeper support
YUTO and ZRP move design, structural engineering and process development forward into customers’ new-product workflows. Hexing Packaging and Nanwang use regional manufacturing and multi-SKU delivery to enter customers’ day-to-day supply chains. JIHONG CO provides a boundary case in which manufacturing and digital commerce operate in parallel, while Lido’s water-based coated paper cups create demand for a broader range of supporting solutions. The shared direction is a move from “winning one order” to “participating in more products and more stages.” This growth line should be assessed not only by customer count, but also by the number of categories supplied to the same customer, share of orders, renewal rate, receivables efficiency and operating cash flow.
Peer evidence / INDUSTRY ECHO
MYS Group: Organizing dispersed packaging interfaces into a coordinated chain that customers can call upon. From design and testing to third-party procurement, inventory, logistics and on-site packaging support, MYS Group connects multiple interfaces that customers would otherwise coordinate themselves. This moves the packaging supplier from product delivery toward process coordination.
Sources: MYS Group 2025 Annual Report; official description of MYS Group capabilities
Pando: Keeping complexity inside the factory and giving customers certainty. Pando organizes material selection, structural design, printing and cup forming, quality standards and multi-site delivery as one customer system, giving a brand’s new cup formats, applications and materials a better path from concept to stable mass production.
Sources: Pando website; Pando development history and manufacturing system; GB/T 44834—2024
Growth line / GROWTH LINE 02
Increasing value per package: From selling products to delivering outcomes
Packaging value comes not only from the amount of material used, but also from the speed of a brand launch, protection of the contents, production-line speed, yield, inventory and logistics cost. Hengxin’s vertical manufacturing, Otor Technology’s food-container engineering and the industry possibilities opened up by Lido’s water-based coated paper cups all advance materials and processes toward finished-product performance. Genuine increases in value per unit must be demonstrated jointly by gross margin or unit contribution, yield, total customer cost, stable mass production and repeat orders; they cannot be inferred from technology displays or the number of certifications.
Peer evidence / INDUSTRY ECHO
Great Shengda: Continuously extending the value radius of corrugated manufacturing. Multiple sites, make-to-order production and flexible scheduling protect efficiency, while design, premium printing and applications such as liquor packaging increase value density. Great Shengda is not leaving its corrugated platform; it is expanding the range of customer outcomes that the platform can support.
Sources: Great Shengda 2025 Annual Report; Great Shengda digital-intelligence practices
Shanghai Ailu: Turning an industrial paper sack into a risk-control interface for a powder-production line. Shanghai Ailu brings paper-sack structure, moisture and barrier protection, and intelligent filling systems into the same problem, allowing packaging to help manage risks at the interfaces between contents and production during filling, sealing, handling and storage.
Sources: Shanghai Ailu 2025 Annual Report
Growth line / GROWTH LINE 03
Expanding application scope: Letting engineering determine material boundaries
ZX Packing Group advances scaled plant-fiber manufacturing through a specialized system, while Homelink broadens customer choice through a multi-material platform. Otor Technology reminds the industry that material solutions must serve the contents, production method and real cost. Application expansion does not mean pushing one material into every use. It means adding qualified solutions that withstand validation of function, manufacturing, compliance and end-of-life pathways, and ultimately deliver new qualified SKUs, commercial-line efficiency, capacity utilization, category-level profitability and repeat orders in new applications.
Peer evidence / INDUSTRY ECHO
BXL Creative Design: Translating a brand story into a commercial product that can be manufactured reliably. It connects brand strategy, cultural interpretation, structural materials, process validation and product delivery, enabling an engaging concept both to be seen by consumers and to be reproduced continuously and accurately by a factory.
Sources: BXL Creative Design 2025 Annual Report; official BXL Creative Design profile
SuperMix: Enabling corrugated packaging to change roles between transport and the retail shelf. From shipping cartons and printed boxes to paper display stands and display boxes, SuperMix places transport protection and retail presentation in one product system, allowing packaging to continue supporting display, recognition and in-store communication after the product reaches the store.
Sources: SuperMix 2025 Annual Report; SuperMix website
Evidence boundary | The six peer companies are used only to identify capabilities and their mechanisms for creating customer value. They do not provide a basis for inferring current orders, profit, market share or the complete realization of a project. Business and product conclusions remain subject to annual reports, finished products and the stated scope of application.
VALUE VALIDATION
From capability to repeat orders | How a solution is truly realized
For a new solution to become a customer order, it must answer a sequence of questions: Does it perform in the real application? Can it be mass-produced reliably on a commercial line? Can the finished product complete the required compliance assessment in the target market? Is the end-of-life pathway workable after use? Is the total cost per qualified package acceptable?
A material sample answers the initial question, “Is it feasible?” The finished product, commercial line and repeat orders answer the further questions, “Can it be manufactured, can it be used and can it be scaled?” The closer a solution is to the customer’s operation, mass-production data and evidence of repeat orders, the more robust its value becomes.
CONCLUSION
Customers do not buy a position on materials; they buy sustainable packaging.
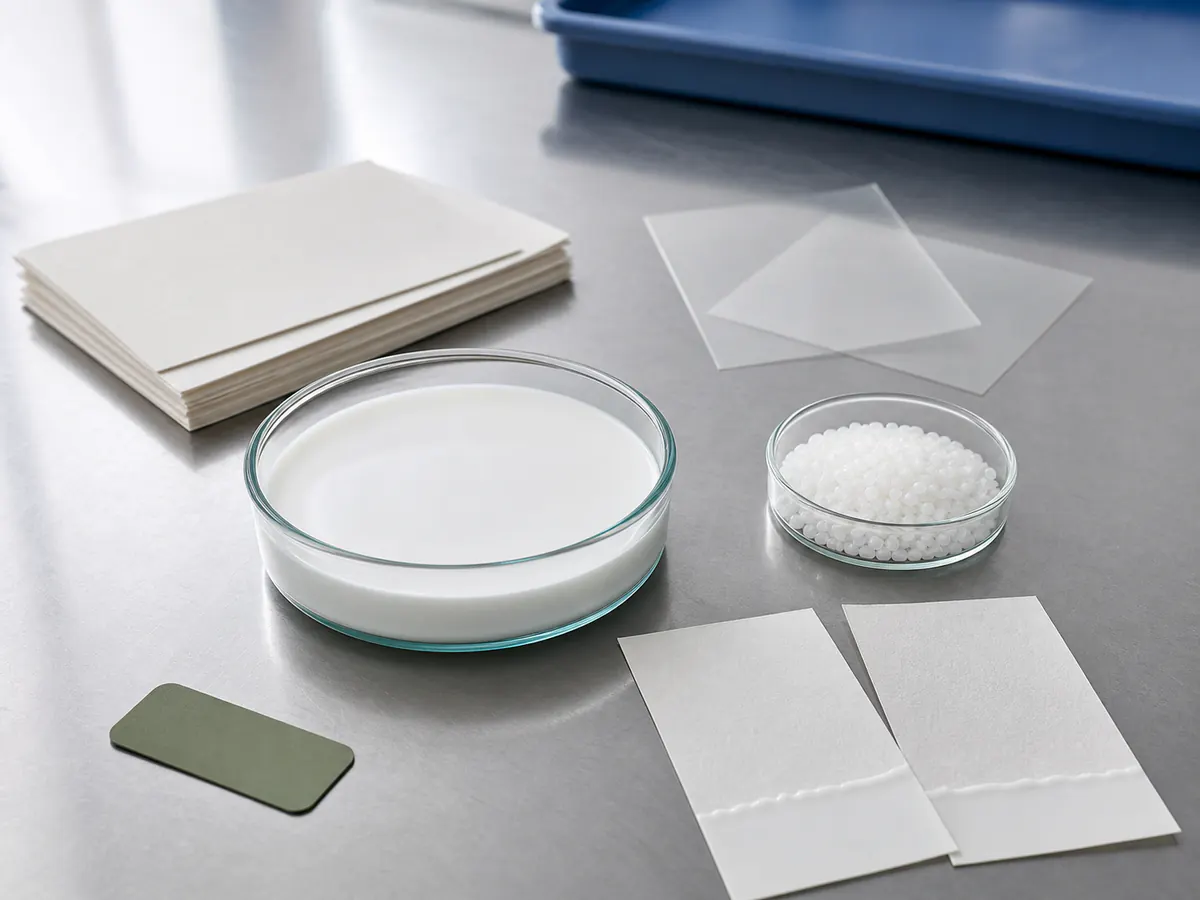
Examining 10 core samples through five value-creation pathways, then considering evidence from six peers, shows that the basic unit of competition in fiber-based packaging is changing. Customers no longer need only an individual sheet of paper, a resin pellet or a forming machine. They need a capability system that connects materials, design, manufacturing, compliance and delivery.
These companies do not share a single answer. Some bring brand creativity into mass production; some organize networks and multi-SKU manufacturing into delivery certainty; some advance materials into real container engineering; some broaden customer choice through specialization or multi-material platforms; and some explore measurable connections between a manufacturing platform and digital commerce. The pathways differ, but the criteria are the same: deeper customer relationships, higher value per unit, broader application scope, and ultimately profit, operating cash flow and repeat orders.
A constructive assessment of a company does not mean ignoring lower revenue, pressure on profit, changes in cash flow or the ramp-up of a production site. A more measured and valuable judgement recognizes the operating platform already in place, the capabilities being released and the outcomes that remain to be realized.
The next phase of growth, therefore, is neither paper replacing plastic nor plastic replacing paper. Once each material is put where it performs best, what matters is turning the right material into qualified packaging and then turning qualified packaging into sustainable customer value.
This conversion—from materials to products, from manufacturing to customers, and from capabilities to business outcomes—is precisely what BIOTEN Packaging follows. Every performance claim should correspond to its manufacturing conditions, every environmental claim to its evidence boundary, and genuinely sustainable innovation should enter the customer’s operation more reliably.
RESEARCH NOTE
BIOTEN Packaging · Industry Insights · Research note
This article uses 10 companies as purposively selected core observation samples and six companies as peer evidence under three growth lines. Neither group constitutes a ranking, an inclusion designation, investment advice, a legal opinion or a conclusion on product compliance. The five value-creation pathways and three growth lines are editorial analytical frameworks and may overlap. JIHONG CO is treated as a boundary case in business models and is not compared on a like-for-like basis with the first four manufacturing and delivery pathways. Group revenue, segment revenue, planned capacity, actual output, certified values and disclosures by unlisted companies are not compared across inconsistent reporting scopes.
Facts, disclosures in annual reports or prospectuses, statements on corporate websites, certification-database records and this article’s analysis are treated separately. Project commissioning, partnerships, exhibition displays, technical exchanges, participation in standards, production licences and certification records do not automatically demonstrate full capacity utilization, stable orders, market ranking or compliance of all company products. Claims involving food contact, recyclability, compostability, PHA or water-based barriers must be assessed against the target market, finished product, specific SKU, test method and valid scope of the certificate.
DATA & VERIFICATION
Data and verification sources
Core operating data are drawn primarily from company 2025 annual reports, prospectuses and exchange announcements, together with corporate websites. Information cut-off date: 16 August 2026.
BIOTEN Packaging · Industry Insights
From materials to products, from manufacturing to customers, and from capabilities to business outcomes.
Customers do not buy a position on materials; they buy sustainable packaging.