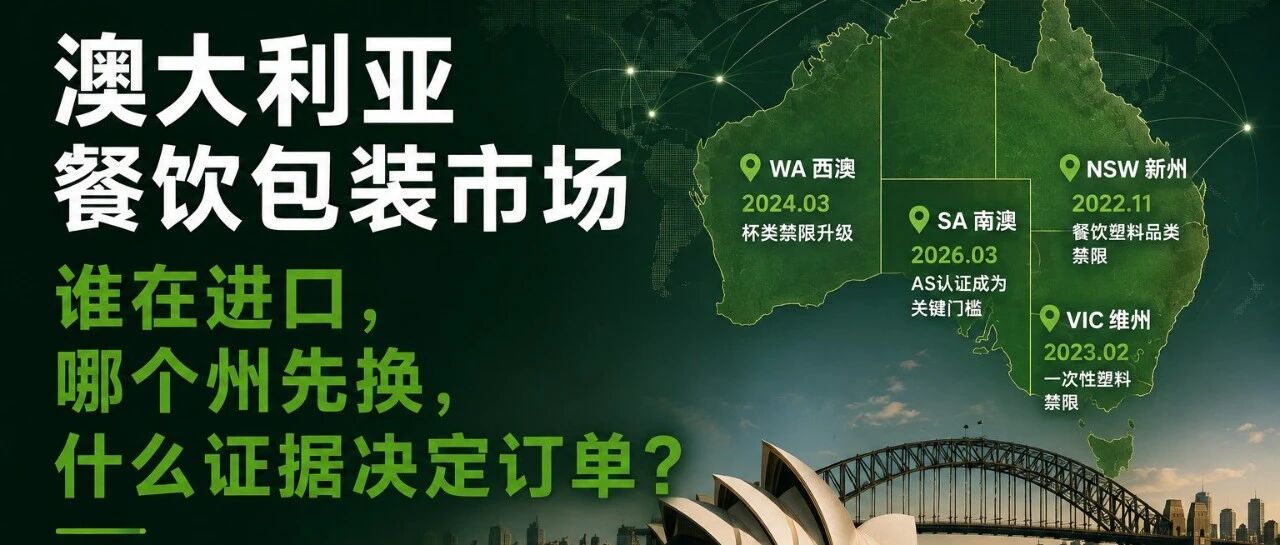
Australia is not a single, uniform market, but a collection of state-level markets in which orders are shaped by state regulations, final-product certification and local end-of-life systems.
GLOBAL FOODSERVICE PACKAGING POLICY AND MARKET MAP / AUSTRALIA MARKET
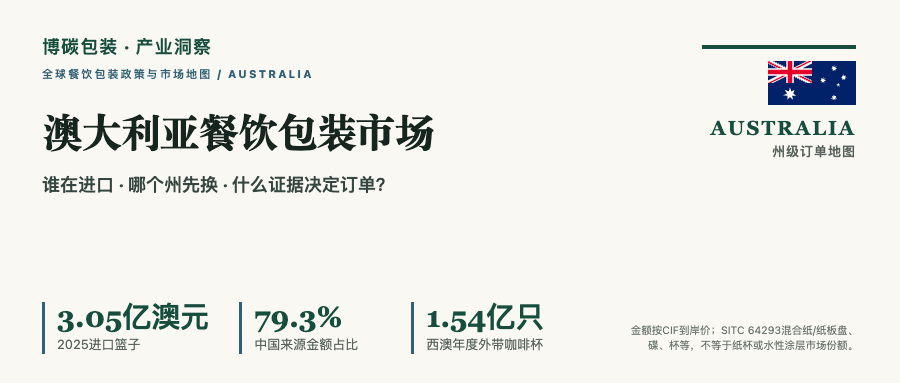
Australia's Foodservice Packaging Market
Who Imports, Which State Moves First
What Evidence Wins the Order?
Official import records, state-level restrictions, AS and ABA certification, FOGO end-of-life requirements and the procurement chain together determine how Chinese materials suppliers, coated-paper producers and cup-and-container manufacturers can enter Australia's foodservice packaging market.
AUD 305 million 2025 import basket · 79.3% value share sourced from China · 154 million takeaway coffee cups used annually in Western Australia
Values are reported on a CIF basis. SITC 64293 is a mixed basket; source-country shares do not represent market shares for paper cups or water-based coatings.
01 · EDITORIAL QUESTION
Is Australia an Import Opportunity or a Certification Maze?
Australia's appeal begins with an import chain that already exists. In 2025, imports of paper or paperboard trays, dishes, cups and related articles under SITC 64293 were approximately AUD 305 million. About AUD 242 million came from China, representing 79.3% of the total value. Because the category covers several kinds of articles, including trays, dishes and cups, these figures indicate sourcing patterns rather than the size of the paper-cup or water-based-coating market.
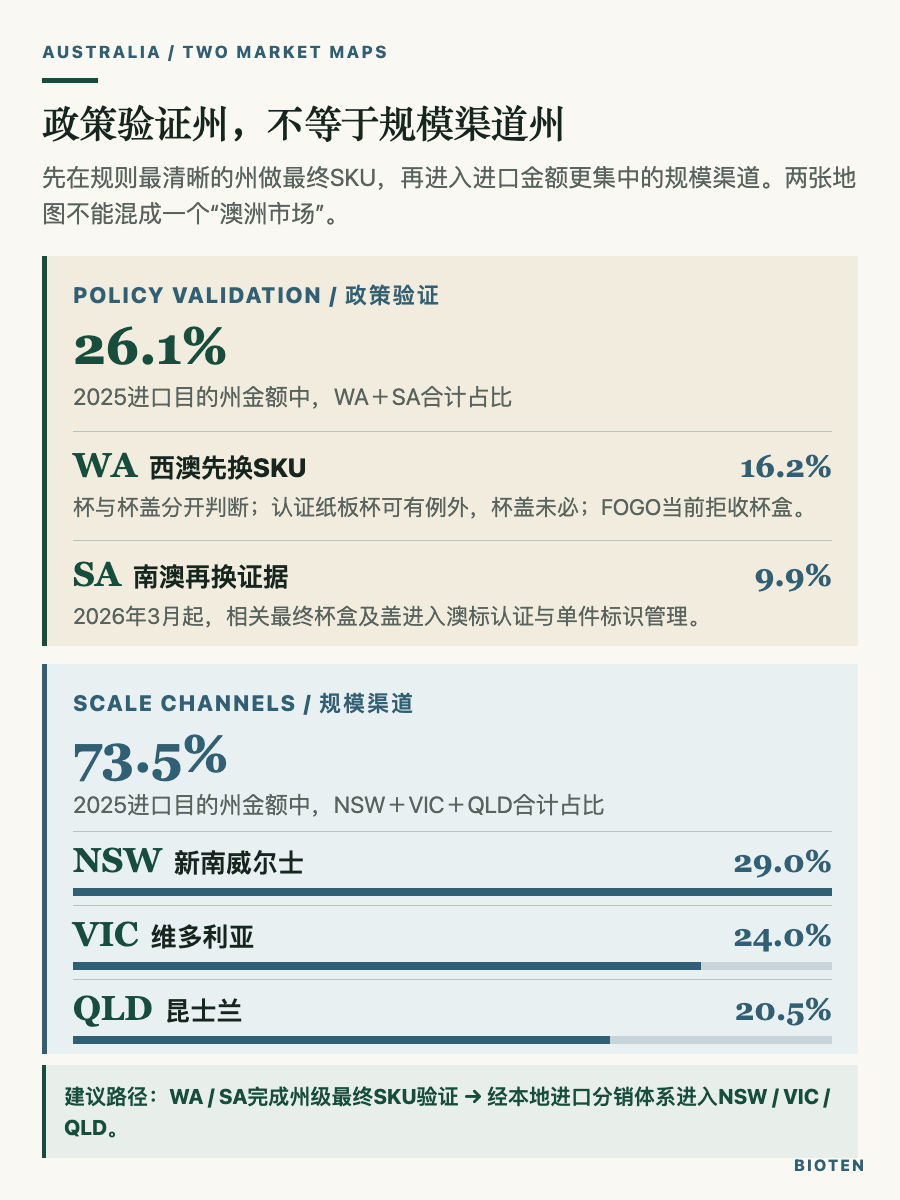
Volume and policy, however, sit on different maps. Western Australia and South Australia are using state-level rules to reshape the construction, certification and labelling of cups, lids and food containers. Meanwhile, New South Wales, Victoria and Queensland together accounted for 73.5% of import value by destination state in 2025. Western Australia and South Australia are logical markets for initial compliance validation; scaling sales requires access to channels in New South Wales, Victoria and Queensland. The sequence matters.
Western Australia also illustrates why supply eligibility and end-of-life acceptance must be assessed separately. Certain paperboard cups certified to an applicable Australian Standard may qualify for a supply exemption, yet the state's 2026 FOGO guidance still directs compostable cups, containers and trays to general waste. Certification answers whether a product may be supplied under an exemption; the local waste system determines where it goes after use. One certificate cannot replace both assessments.
CORE ASSESSMENT
Australia is not a greenfield market. China is already the principal source within the relevant import basket; the next contest is over specification redesign. Western Australia and South Australia are suited to validating state compliance and final-product evidence, while New South Wales, Victoria and Queensland provide the larger sales channels. Suppliers that can deliver verified construction, food-contact compliance, certification, labelling and a credible end-of-life route are the ones most likely to reach the next round of procurement.
SCOPE OF THE REVIEW
This article was verified through 17 August 2026. Import data are drawn from Australian Bureau of Statistics customs records for SITC 64293 and reported on a CIF basis. The category covers paper or paperboard trays, dishes, cups and similar articles under HS 482361 and HS 482369. It excludes moulded-pulp articles under HS 482370 and does not capture all coated paper imported under headings such as HS 4811 and subsequently converted into cups in Australia. Import value, weight and source-country shares are not market-share measures for paper cups, water-based coatings or the Australian packaging market as a whole. The federal framework and the rules in South Australia and Western Australia were reviewed in full; other states are compared only to the extent supported by verified official sources.
02 · MARKET DATA
This Is Not an Empty Market Waiting for Chinese Entrants
In 2025, imports under SITC 64293 totalled approximately AUD 305 million and 85,100 tonnes. China accounted for about AUD 242 million and 66,500 tonnes, equal to 79.3% of import value and 78.1% of recorded weight. In 2024, imports under the same classification were approximately AUD 316 million, with China representing 77.1% of value. By 2025, total value had fallen 3.3% and weight 1.1%; imports from China declined 0.5% in value but increased 3.7% in weight. The data point to adjustments in price, product mix and sourcing within a mature market, not to a demand surge created simply by plastic restrictions.
China's share of import value increased by about 2.2 percentage points in one year. Other leading sources in 2025 were Indonesia at 7.3%, Taiwan at 6.5% and Vietnam at 4.7%. China has a clear supply advantage, but buyers retain several Asian alternatives. Structural compliance, dependable delivery and local inventory therefore affect both procurement negotiations and the ability to retain repeat business.
From January through April 2026, imports in the basket were approximately AUD 88.15 million and 25,900 tonnes, down 17.3% in value and 3.4% in weight year on year. The sharper decline in value warrants continued monitoring of pricing pressure and product-mix changes, but four months of data cannot be extrapolated to the full year or used to conclude that Australian foodservice-packaging demand is contracting.
Sea freight accounted for 99.7% of 2025 import value. Orders are therefore judged not only on ex-works price, but also on an importer's shipping plan, inventory position, interstate distribution and version control. Destination-state shares were New South Wales 29.0%, Victoria 24.0%, Queensland 20.5%, Western Australia 16.2% and South Australia 9.9%. New South Wales and Victoria together represented 53.0%, making them the principal scale channels. Western Australia and South Australia together represented 26.1%, enough to support state-specific compliance validation.
Demand-side use cases are also verifiable. The ABS recorded seasonally adjusted turnover of approximately AUD 5.582 billion for Australian cafés, restaurants and takeaway food services in June 2025. The Western Australian Government reports that the state uses more than 154 million takeaway coffee cups each year. The first figure is one month's foodservice turnover and the second is a state-level cup count; neither is the size of the packaging market. They do, however, indicate the scale of the channel and the exposure of cup-related SKUs.
Australia also has domestic production. Detmold Group is headquartered in South Australia and manufactures paper and paperboard food packaging in Australia and across Asia. Huhtamaki Australia publicly describes local capacity for paper cups, containers and plates. The market combines domestic manufacturing, multinational operations and import distribution. Chinese suppliers compete not only with one another, but also with sources in Indonesia, Taiwan and Vietnam and with Australian converting capacity.
Principal sources: ABS international merchandise-trade records, 2024–2026; ABS, Retail Trade, Australia, June 2025; Western Australian coffee-cup fact sheet; official information from Detpak and Huhtamaki.
03 · FEDERAL LAYER
The Federal Framework Assigns Responsibility; States Decide Whether a Cup or Container May Be Supplied
As of March 2026, Australia's proposed national packaging regime remained under development. The Department of Climate Change, Energy, the Environment and Water (DCCEEW) states that existing co-regulatory arrangements will continue until the new regulations commence. The federal layer establishes packaging responsibilities; whether a particular cup or container may be supplied still depends on state or territory product rules and the relevant local end-of-life system.
The current national foundation consists of the National Environment Protection (Used Packaging Materials) Measure 2011 and the Australian Packaging Covenant.
DCCEEW currently explains that businesses manufacturing or selling packaging in Australia with annual turnover of AUD 5 million or more must join APCO, report under state or territory arrangements implementing the NEPM, or participate in an approved program delivering equivalent outcomes. A factory in China may manufacture the product, but the Australian importer, brand owner or first seller must determine its own obligations. Those obligations flow upstream as requirements for construction, origin data, environmental claims and annual reporting.
The Australian Government reports that about 6.84 million tonnes of packaging were placed on the market in 2023–24, of which 41% ultimately went to landfill. This is an all-packaging figure used only to describe national material flows. Reduction, reuse, design for recycling and chemicals management are directions of federal reform, but they should not be presented as an already operative, nationally uniform product rule. Export quotations must first identify the final state of receipt.
Principal sources: DCCEEW, Taking Responsibility for Our Packaging, Reforming Packaging Regulation and A Circular Economy for Packaging in Australia; NEPM; APCO.
04 · WESTERN AUSTRALIA
Western Australia Changes the SKU First: A Cup May Qualify, but Its Lid May Not
Western Australia is a practical first validation market for cup-and-container manufacturers because product scope and implementation dates are comparatively clear.
Under the Environmental Protection (Prohibited Plastics and Balloons) Regulations 2018 and the state's Plan for Plastics, single-use plastic cold-drink cups were covered from 1 October 2022; hot-drink cups and all single-use plastic cup lids from 1 March 2024; lidded takeaway or dine-in containers, bowls, trays and related plastic lids from 1 September 2024; and moulded or cut expanded-plastic packaging from 1 July 2025.
Western Australia assesses product composition rather than marketing terminology. Products made wholly or partly of plastic may fall within scope, including lined, coated and laminated structures. A product is not excluded simply because it is described as plant-based, biodegradable or water-based. The regulations also connect supply to the recipient in Western Australia; an overseas factory cannot avoid the rules merely by pointing to the place of contract or the supplier's location.
Cups and lids must be assessed separately. A paperboard cup certified as a complete product to a current AS 4736 or AS 5810 scheme may qualify for a specific statutory exemption. Cup lids do not enjoy the same general exemption. The current Western Australian provision for certified paperboard lids applies to lids for food containers, trays and bowls, but not to cup lids; official guidance also requires coffee-cup lids to be entirely plastic-free. Certification of the cup body does not automatically cover its lid, and one non-compliant accessory can disqualify the complete SKU.
As of 17 August 2026, Western Australia retained a temporary class exemption for certain takeaway containers and lids used for pourable soup or other liquid food served above 60°C. The official listing showed an expiry date of 31 August 2026, only 14 days after the verification date. Products for soup, curry, laksa and similar applications must therefore be rechecked before quotation and shipment. A temporary exemption should never be embedded in a long-term product manual.
Principal sources: current Western Australian Regulations; Plan for Plastics; coffee-cup and cup-lid fact sheets; temporary exemption SUP0003/2024/2.
05 · SOUTH AUSTRALIA
South Australia Changes the Evidence Next: From 2026, Item-Level Labelling Also Matters
South Australia's focus is evidence and labelling. From 1 September 2024, hot- and cold-drink cups, cup lids and relevant containers for ready-to-eat food entered a new regulatory phase. A paper-based cup or container with plastic extrusion coating, an aqueous coating or a water-applied barrier layer is not automatically plastic-free merely because it is described as water-based or predominantly fibre.
From 1 March 2026, relevant certified-compostable food and beverage containers seeking an exemption must follow a current AS 4736 or AS 5810 certification route and clearly identify, on each individual item, whether the product is home compostable, industrially compostable, or both. Marking only the outer carton is insufficient. Containers below 60 mL and lids below 70 mm in diameter may qualify for limited marking-condition exceptions, but the exceptions do not remove certification or record-keeping obligations from the entire product line.
South Australia also retains narrowly defined transitional exceptions for certain clear, separable PP or PET lids and high-temperature soup containers. The market will not converge on a single material. Western Australia first alters the cup-and-lid SKU; South Australia then pushes certification, labelling and version control down to the individual item.
New South Wales, Victoria and Queensland also restrict selected single-use plastic products, but their scopes are not identical. New South Wales covers specified plates, bowls, cutlery and expanded-polystyrene foodservice articles, and plastic linings or coatings may be relevant to classification; some lidded bowls fall outside particular categories. Victoria expressly covers plastic plates, including paper plates with plastic linings, as well as EPS food and beverage containers. Queensland focuses on plastic plates, open bowls, cutlery and EPS cups and containers. These states provide larger channels, but South Australian and Western Australian certification logic cannot simply be copied into them.
Principal sources: South Australian Act and current Regulations; Replace the Waste labelling guidance; official guidance from NSW EPA, EPA Victoria and Business Queensland.
06 · CERTIFICATION
AS and ABA: Evidence at One Level Does Not Automatically Replace Evidence at the Next
AS 4736—2006 covers commercial or industrial composting and other controlled microbial treatment, while AS 5810—2010 covers home composting. The two standards are not interchangeable. Standards are generally voluntary until a state regulation incorporates one as a condition of an exemption for a defined product. Standards Australia develops standards but does not issue product certificates. The Australasian Bioplastics Association (ABA) is a certification body and industry organisation, not a legislature.
ABA's public FAQ highlights several easily overlooked boundaries. A supplier's certification does not automatically certify its customer's finished product. Use of a certification mark is not automatically transferable and may require a trademark sublicense. Whether the thickest product represents an entire formulation family is subject to independent review, and the application must include the inks, colourants and additives actually used. State exemptions look at the certificate holder, product name, standard, thickness, formulation, printing, accessories, validity period and authorised scope of mark use.
Evidence should be separated into three levels. Material-level evidence can establish the properties of a resin or coating formulation. Coated-paper evidence can define the base paper, coat weight and barrier construction. Only final-product evidence captures the cup bottom, side seam, rim, ink, adhesive, label, lid and actual maximum thickness within the same SKU. Evidence at one level can support, but cannot replace, evidence at the next.
Food-contact compliance must be assessed independently. Clause 9 of FSANZ Standard 3.2.2 requires a food business to use packaging that is fit for its intended use and unlikely to contaminate food. Food type, acidity or fat content, contact time, temperature, heating or microwave use, freezing and reuse can all change the evidence required. AS or ABA certification does not substitute for food-contact compliance, and food-contact documentation does not establish compostability, fibre recyclability or eligibility for a state exemption.
PFAS claims also require restraint. The federal government is considering future restrictions on packaging chemicals, and APCO's work on PFAS in fibre-based food-contact packaging remains an industry initiative and a subject of 2026 consultation, not a nationally uniform prohibition covering all food packaging. ABA processes may review total fluorine and declarations concerning intentionally added fluorinated substances, but participation in an ABA process should not be marketed as proof of “zero PFAS”.
Principal sources: Standards Australia; ABA FAQ and sublicensing rules; FSANZ food-packaging guidance and Standard 3.2.2; DCCEEW and APCO PFAS materials.
07 · END OF LIFE
Certified, Yet Still Excluded from Western Australia's FOGO System—Why?
Western Australia's 2026 FOGO guidance accepts food, garden organics and certified kitchen caddy liners bearing the AS 4736 mark. Food packaging is outside the accepted stream. Non-recyclable packaging—including compostable cups, containers and trays—is currently directed to general waste. The official rationale is not that certification is invalid, but that kerbside systems cannot reliably distinguish certified packaging from non-certified packaging and must control contamination from plastics, coatings and chemicals.
Certification and end-of-life systems answer different questions. Certification may determine whether a particular paperboard cup can be supplied under a state exemption. Local governments, treatment facilities, licence conditions and collection contracts determine whether the used product may enter FOGO. Some South Australian councils offering green-organics services may accept certified packaging bearing an applicable Australian Standard mark. The same certificate can therefore lead to different outcomes in different states and local systems.
Environmental marketing is consequently part of the order threshold. The Australian Competition and Consumer Commission (ACCC) requires environmental claims to be truthful, evidence-based and clear about the conditions under which they apply. Its official guidance uses takeaway coffee cups to show that a claim may mislead consumers if a cup can be handled only through a dedicated collection point but is presented as suitable for ordinary recycling. The Australian market assesses the product, the label, the disposal graphic and the sales language.
Certification answers, “May this product be supplied under an exemption?” The end-of-life system answers, “Where does it go after use?” A commercially viable order must answer both.
Principal sources: WA Waste Authority, Towards Cleaner Compost; Which Bin SA; ACCC environmental-claims guidance; ABA FAQ.
08 · ORDER CHAIN
Who Imports, Who Pays, and Who Can Reject the SKU?
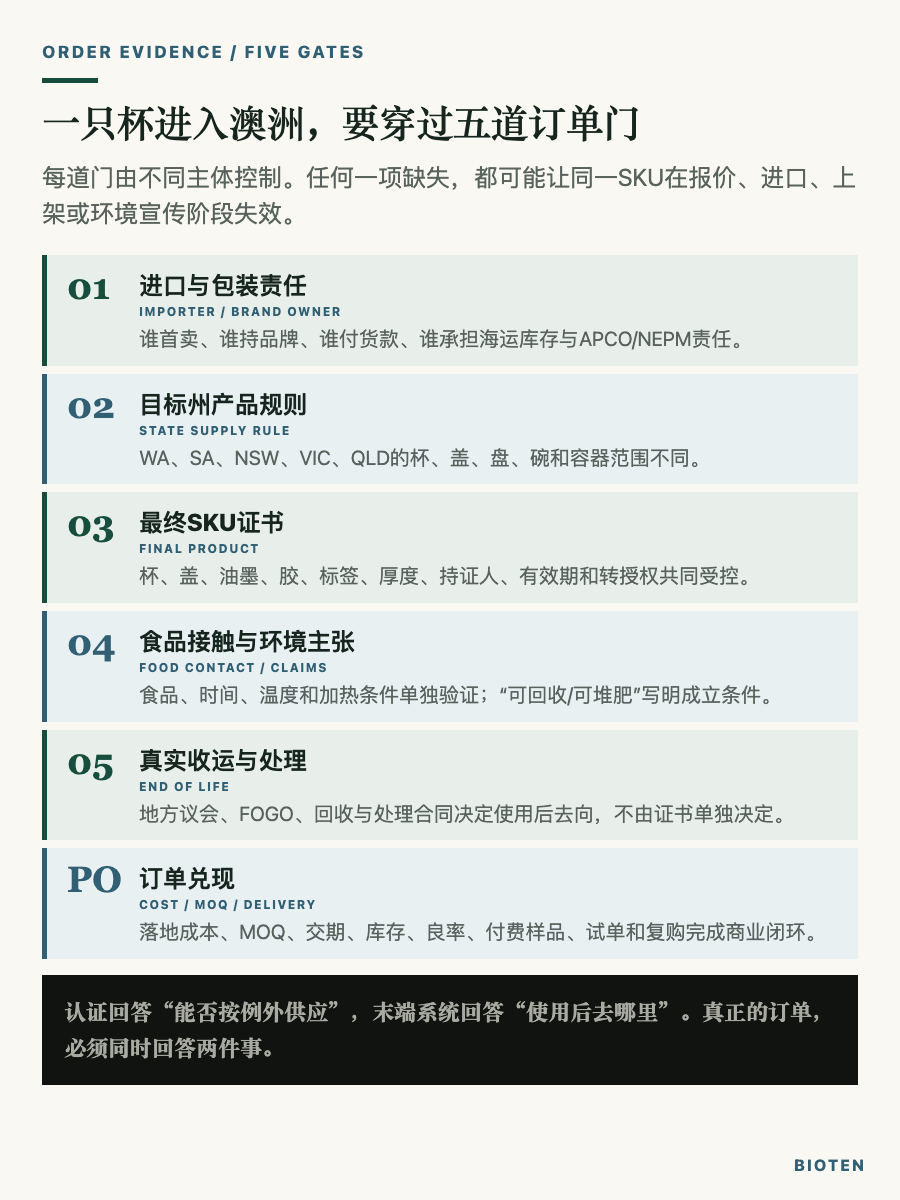
ABS customs records disclose source country, value, weight, transport mode and destination state, but not a company-level ranking of importers. Public evidence can identify roles; it cannot support a credible “Top 10 importers” list. Australian packaging brands, importers and distributors typically convert a foodservice brand's functional, printing, cost and environmental objectives into an SKU, select the source country and manage ocean freight, inventory and interstate delivery. Local converters purchase materials or coated paper and manufacture the finished cups and containers.
Two order routes are common. The finished-product route runs from a Chinese cup or container manufacturer to an Australian packaging brand or importer, then through a distributor to cafés, quick-service restaurants, hotels, supermarkets or institutional customers. The material route runs from a Chinese materials supplier or coated-paper producer to an Australian or offshore converter, then to a packaging brand or importer and finally to the foodservice channel. The importer may not be the brand owner, and the party paying for the order may not be the entity responsible under the federal packaging framework. Contract terms and brand ownership must be checked separately.
Specifications are usually set by foodservice chains, coffee brands, packaging brands or institutional procurement teams. Chinese suppliers are commonly paid by Australian importers, packaging distributors or converters. State regulators determine whether the product may be supplied; ABA and laboratories determine the scope of certificates and tests; food businesses control safe use; local governments and treatment facilities determine the end-of-life route. Any of these parties can reject an SKU, but for different reasons.
Before quoting, suppliers should identify the final state of receipt; the importer or first seller; the brand owner and payer; the full construction of cup and lid; food type and temperature; certificate holder; item-level labelling; intended end-of-life route; sea-freight minimum order quantity; delivery lead time; inventory arrangements; and responsibility for changes. Regulation becomes commercial evidence only when it is reflected in a formal specification, paid sampling, third-party testing, a trial order or repeat purchasing.
Principal sources: ABS customs records; DCCEEW and APCO packaging-responsibility materials; FSANZ; South Australian and Western Australian implementation guidance; publicly available corporate supply-chain information.
09 · CHINA ENTRY
How Can Three Types of Chinese Suppliers Reach the Next Round?
Materials suppliers: deliver a controlled-composition and use-window dossier. It should identify the dry-film polymer, solids content, coat weight, residual monomers, crosslinkers and additives, restricted substances, PFAS and total-fluorine boundaries, food simulants, temperature and contact time. External claims should state that the material and technical package supports validation of the final SKU. “Water-based” or “bio-based” alone cannot substantiate claims of plastic-free status, compostability, recyclability or state-level market access.
Coated-paper producers: deliver three evidence sets—performance, converting and end of life. Fix the base paper, basis weight, coating formulation, dry-film mass, thickness and roll batch. Provide Cobb and KIT results, heat-seal performance, crease resistance, edge-wicking data and printing and cup-forming parameters. Where fibre circularity is claimed, report total screening yield, rejects, DCS or COD, stickies and resulting paper quality separately. Repulpability evidence does not replace the AS pathway required in South Australia or Western Australia, nor does it prove acceptance by a local Australian waste system.
Cup and paper-container manufacturers: deliver a final-SKU responsibility package in the condition actually sold. Control the cup or container, lid, ink, adhesive, label, sticker, dimensions, maximum thickness and transport packaging. Keep the certificate holder, certificate number, standard, validity period and authorised mark use consistent. Prepare item-level marking for South Australia and assess the cup and its lid separately for Western Australia. Food-contact evidence must cover the actual food and temperature. Any change in factory, formulation, thickness or accessory requires reassessment.
Commercial entry should not begin with the idea of a single “all-Australia cup”. A practical sequence is to validate one state, one accountable importer, one final SKU and one real end-of-life route in Western Australia or South Australia, then use local import and distribution systems to reach the larger channels in New South Wales, Victoria and Queensland. For finished-product manufacturers, sea-freight MOQ, landed cost per thousand units, inventory and replenishment capacity matter as much as certification. For materials and coated-paper suppliers, local converting partners and cup-forming yields are earlier control points.
10 · CONCLUSION
What Australia Actually Buys Is a Low-Risk SKU
For Chinese supply chains, the threshold for the Australian market has shifted from “we can make a paper cup” to “we can deliver a compliant final SKU state by state”. Official 2025 import records show that China is the principal source within the relevant basket of paper-based foodservice articles. State rules are moving competition beyond unit price toward construction, certification, food-contact compliance, labelling, inventory and end-of-life instructions.
Western Australia's annual use of more than 154 million takeaway coffee cups does not translate into the same number of substitution orders. A more realistic objective is to complete one evidence-closed-loop cup: the target state and accountable importer are identified; cup and lid are assessed separately; the finished product can be manufactured consistently; food use is substantiated; and environmental instructions match the local bin system. An SKU that meets those conditions has a credible chance of entering the next round of Australia's mature supply chain.
BIOTEN PACKAGING · INDUSTRY INSIGHT · RESEARCH NOTE
This article is based on Australian legislation, government statistics, standards, certification-body materials and official corporate information verifiable through 17 August 2026. Dynamic exemptions, certificate status and local acceptance must be rechecked for the target state and final SKU before quotation or shipment. The article is intended for industry research and market assessment and does not constitute legal, certification, product-performance or order advice.
Data and verification sources
Federal packaging responsibility: DCCEEW, Taking Responsibility for Our Packaging; status of packaging-regulation reform; circular-economy materials; NEPM 2011; APCO Covenant.
Market and trade: ABS international merchandise-trade datasets and import-detail resources; ABS, Retail Trade, Australia, June 2025; UN SITC Rev. 4; official information from Detpak and Huhtamaki Australia.
Western Australia: current Regulations, Plan for Plastics, takeaway-coffee-cup and cup-lid fact sheets, final-product certification guidance, temporary exemptions and current FOGO guidance.
South Australia: 2020 Act, current 2021 Regulations, beverage-container and food-container guidance, 2026 labelling requirements and Which Bin SA.
Other states: NSW EPA single-use-plastics FAQ, EPA Victoria and Business Queensland.
Certification, food contact and environmental claims: Standards Australia AS 4736; ABA FAQ and sublicensing rules; FSANZ food-packaging guidance and Standard 3.2.2; DCCEEW sustainable-packaging and PFAS materials; APCO PFAS updates; ACCC environmental-claims guidance.